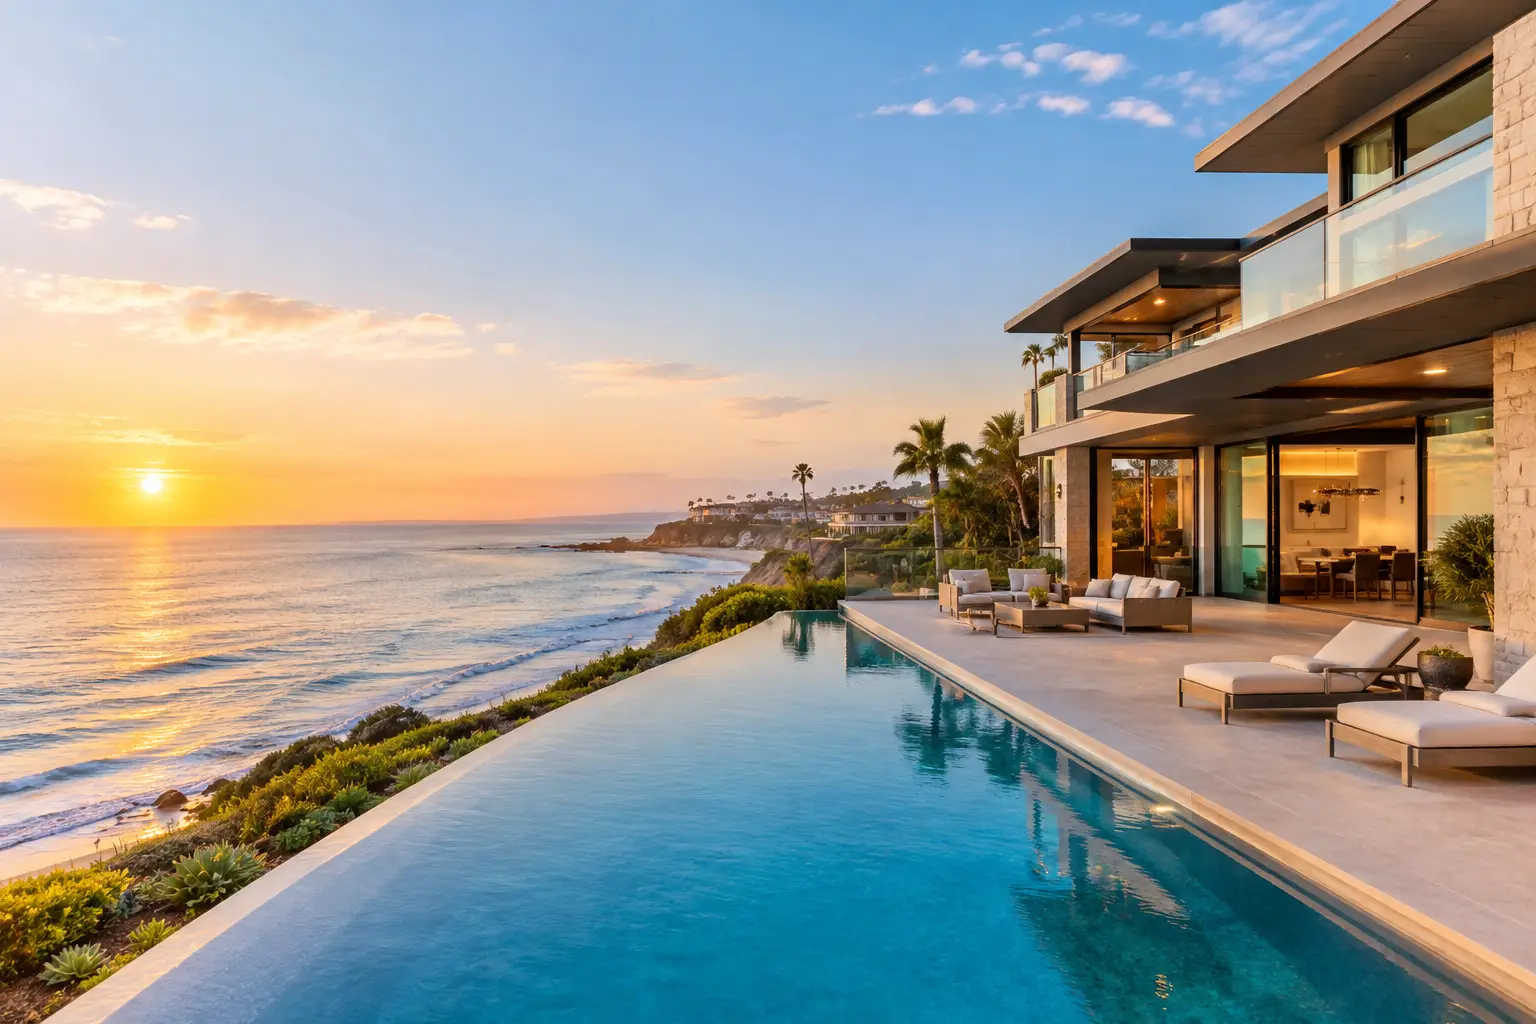
A gulf view may command attention, but it does not automatically command a premium that holds through changing market conditions. In luxury coastal real estate, the strongest assets combine emotional appeal with defensible fundamentals: a scarce setting, functional design, favorable access, disciplined operating costs, and a clear buyer pool when it is time to sell.
Along Florida’s 30A corridor, South Walton, Panama City Beach, and the broader Emerald Coast, the distinction matters. Buyers are not only evaluating square footage and finishes. They are underwriting lifestyle, rental potential, storm exposure, insurance costs, walkability, beach access, and the future supply of comparable properties. The best decisions begin by separating a beautiful property from a strategically positioned one.
What Creates Value in Luxury Coastal Real Estate
A luxury coastal property is rarely valued on a single metric. Two homes with similar interiors and asking prices can perform very differently because their locations, revenue profiles, ownership costs, and resale stories are not the same.
The first advantage is scarcity. Gulf-front land is finite, but even within a coastal market, scarcity has layers. Direct beach frontage, protected views, deeded access, proximity to town centers, a private gated setting, and a lot that supports a meaningful home footprint can each create durable differentiation. A new build several blocks from the water may be exceptionally finished, yet it competes with future construction more directly than a well-positioned home on a constrained gulf-front or gulf-view parcel.
Access is equally important. Buyers should look beyond the listing description and understand how the property functions in real life. Is beach access private, deeded, public, or subject to a longer walk? Is there adequate parking for family use and rental turnover? Can guests reach restaurants, shopping, and beach access without crossing a high-traffic corridor? A property that makes the coast easy to enjoy tends to attract stronger end users and guests.
Design also influences performance, particularly in a second-home and vacation-rental market. The properties that retain broad appeal often pair high-quality finishes with practical layouts: multiple ensuite bedrooms, flexible bunk areas, generous outdoor living, an elevator where appropriate, durable materials, and storage for beach equipment. A dramatic architectural statement can be valuable, but only when it supports usability. Highly personal layouts or over-customized interiors can narrow the resale audience.
The View Is an Asset, but Verify Its Protection
A view premium is justified when the view is durable. Before assigning value to a gulf, lake, or preserve outlook, examine what can be built between the home and the water, applicable height restrictions, neighboring parcels, easements, and local development patterns. A view that depends on an empty lot is not the same as a view protected by geography, zoning, or established development.
This is especially relevant in fast-evolving coastal submarkets. Buyers should assess not only the home they see today, but the built environment they may own for the next decade. Sellers who can clearly document view corridors, beach access, and surrounding constraints are better positioned to defend a premium.
Rental Revenue Should Be Underwritten, Not Assumed
For many buyers, the coastal residence is both a retreat and an income-producing asset. That dual purpose can be powerful, but projected revenue should never be treated as a substitute for due diligence.
A credible rental analysis starts with comparable properties, not a generic market average. Size, bedroom count, sleeping capacity, pool configuration, proximity to the beach, condition, parking, and management quality can materially affect gross bookings. A five-bedroom home with a pool and a short beach walk may compete in a different revenue tier than another five-bedroom home a mile inland, even if their acquisition prices appear similar.
Gross revenue is only the beginning. The relevant question is what remains after management fees, cleaning, repairs, utilities, taxes, insurance, reserves, furnishing replacement, and owner use. A property that produces impressive top-line revenue but requires constant reinvestment may deliver a weaker return than a less ambitious property with stable margins and lower operating volatility.
Owners should also evaluate rental restrictions before making an offer. Some communities limit short-term rentals, impose registration requirements, or maintain rules that affect occupancy and guest operations. These policies can enhance a neighborhood’s character and long-term owner appeal, but they may reduce income flexibility. There is no universally correct answer. The right property depends on whether the primary objective is personal use, current yield, appreciation, or a balanced portfolio strategy.
The Cost Side Can Change the Investment Case
Coastal ownership carries expenses that deserve the same scrutiny as purchase price. Insurance availability and premiums, flood zone classification, roof age, wind mitigation features, elevation, building materials, and prior claims history can all shape annual carrying costs.
A lower-priced home is not necessarily the better buy if it carries an outsized insurance burden or needs immediate capital improvements. Conversely, a well-maintained property with a newer roof, impact-rated openings, current systems, and thoughtful storm-hardening may justify a higher acquisition price because it reduces near-term uncertainty.
Buyers should build a realistic reserve for maintenance. Salt air, humidity, wind, and heavy rental use affect exterior finishes, HVAC systems, pools, decks, railings, appliances, and furnishings. The goal is not to avoid these costs. It is to price them into the ownership model before closing, rather than discover them after a season of use.
Four areas merit particular review during due diligence:
- Insurance quotes based on the actual property, not a broad estimate
- Flood-zone, elevation, and drainage documentation
- Roof, window, HVAC, pool, and exterior maintenance timelines
- Rental regulations, association rules, and current management performance
Why Micro-Markets Matter More Than Broad Headlines
The Emerald Coast does not behave as one market. A luxury buyer comparing 30A, Inlet Beach, WaterColor, Rosemary Beach, Seagrove, Santa Rosa Beach, Panama City Beach, and nearby coastal communities is evaluating distinct supply profiles, buyer demographics, rental patterns, amenities, and price expectations.
Broad market headlines can provide context, but they do not establish value for a specific property. A report showing increased inventory may have little relevance to a rare gulf-front home in a tightly held community. Likewise, a strong average sales price does not validate an aggressive list price for a property with dated interiors, compromised access, or a difficult floor plan.
This is where broker-level market intelligence becomes decisive. A meaningful pricing or acquisition strategy requires recent comparable sales, active competition, withdrawn listings, pending activity, days on market, and the reasons buyers are choosing one submarket over another. It also requires judgment. Not every feature that cost money to build will translate into equal resale value.
Positioning a Coastal Property for a Stronger Exit
Luxury sellers often focus on presentation, and presentation matters. Professional photography, thoughtful staging, polished marketing, and a well-maintained exterior shape first impressions. Yet the more strategic work happens before the property reaches the market.
The pricing decision should reflect the property’s actual competitive set, not simply the seller’s desired outcome or the highest nearby sale. In coastal markets, buyers quickly identify when a home is misaligned with its location, condition, rental profile, or view quality. An ambitious price can be appropriate for a genuinely differentiated asset, but it must be supported by a clear narrative and evidence.
Renovation decisions should be selective. Updating kitchens, baths, lighting, outdoor areas, furnishings, and paint can improve marketability when the home feels dated relative to its price tier. Structural changes, highly specialized finishes, or expensive improvements that do not address the buyer’s primary objections may not produce the desired return. The most effective upgrades reduce friction: they make the home feel current, easy to operate, and ready to enjoy on day one.
For buyers and sellers alike, the most valuable coastal decisions are made before emotion takes over. A property should feel exceptional, but it should also stand up to practical questions about access, operating costs, rental performance, competitive supply, and future resale. That is the standard worth applying before making a move on the coast.