A gulf view can add meaningful value to a Florida property, but it also puts the home under a different level of insurance scrutiny. For buyers and investors, understanding what lowers coastal home insurability is not a side issue to address after closing. It is part of the acquisition decision itself – affecting operating costs, financing, renovation priorities, rental economics, and ultimately resale liquidity.
Along 30A, Panama City Beach, and the broader Emerald Coast, two homes with similar square footage and price points can produce very different insurance outcomes. The difference often comes down to the property’s physical condition, exact location, construction details, and documented loss profile. Insurance availability and pricing change over time, so no single feature automatically makes a home uninsurable. Still, certain conditions consistently narrow the carrier pool or increase premiums and deductibles.
What Lowers Coastal Home Insurability Most
Insurance carriers evaluate the probability and severity of a future claim. Coastal homes are exposed to wind, wind-driven rain, floodwater, salt air, humidity, and periods of vacancy. A property that shows weaknesses in any of those areas can be more expensive to insure, subject to restrictive terms, or difficult to place with a preferred carrier.
An aging or compromised roof
Roof age is one of the most consequential underwriting factors in Florida. A roof may look serviceable from the street yet fall outside a carrier’s acceptable age threshold, especially if it is nearing the end of its expected useful life. Insurers also consider material, installation quality, visible wear, prior repairs, and whether the roof has a history of leaks or storm damage.
For a buyer, this can change the economics quickly. A house priced attractively because it needs a roof may still be a sound purchase, but the replacement cost, timing, and potential insurance limitations should be reflected in the offer and the capital plan. Do not assume that a seller’s current policy will indicate what a new buyer can obtain. Underwriting standards can differ at renewal and between carriers.
Distance to the coast and wind exposure
Proximity to the Gulf remains a central factor, but “close to the beach” is not a precise insurance measurement. Carriers may evaluate distance from the shoreline, wind zone, elevation, surrounding terrain, and the home’s exposure to open water. Gulf-front and first-tier properties often face a smaller insurance market because they carry greater potential for hurricane-related loss.
That does not mean premium coastal locations are poor investments. It means buyers should underwrite insurance as a property-specific expense rather than applying a broad percentage of purchase price. A well-built gulf-front residence with modern mitigation features may compare favorably with an older home farther inland that has a deteriorated roof and weak openings.
Limited wind mitigation features
Modern construction methods can materially improve both resilience and insurability. Insurers commonly look for documented wind mitigation measures such as hurricane-rated opening protection, impact-rated windows and doors, reinforced garage doors, roof-to-wall connections, a compliant roof deck attachment, and a secondary water-resistance barrier.
The key word is documented. A buyer should not rely on verbal assurances that windows are impact-rated or that shutters were installed years ago. A current wind mitigation inspection identifies the features present and can support available discounts. In many coastal transactions, this report is as financially useful as a standard inspection because it helps clarify the property’s insurance position before closing.
Prior claims and loss history
A home with multiple water, wind, mold, or plumbing claims may receive closer underwriting review. Even when damage was repaired, carriers may want to know the cause of loss, the scope of work, whether permits were obtained, and whether preventive improvements were made.
Claims tied to recurring water intrusion are especially significant in a humid coastal environment. A repaired ceiling is not the same as a resolved problem. Buyers should investigate whether a prior loss resulted from a one-time event or signals an unresolved issue with roofing, windows, flashing, drainage, plumbing, or building-envelope performance.
A property’s claim record is only one part of the equation. An individual buyer’s insurance history and credit-based underwriting factors, where permitted, can also affect terms. The practical takeaway is to begin insurance conversations early rather than waiting until the final days of due diligence.
Flood Risk Can Change the Ownership Equation
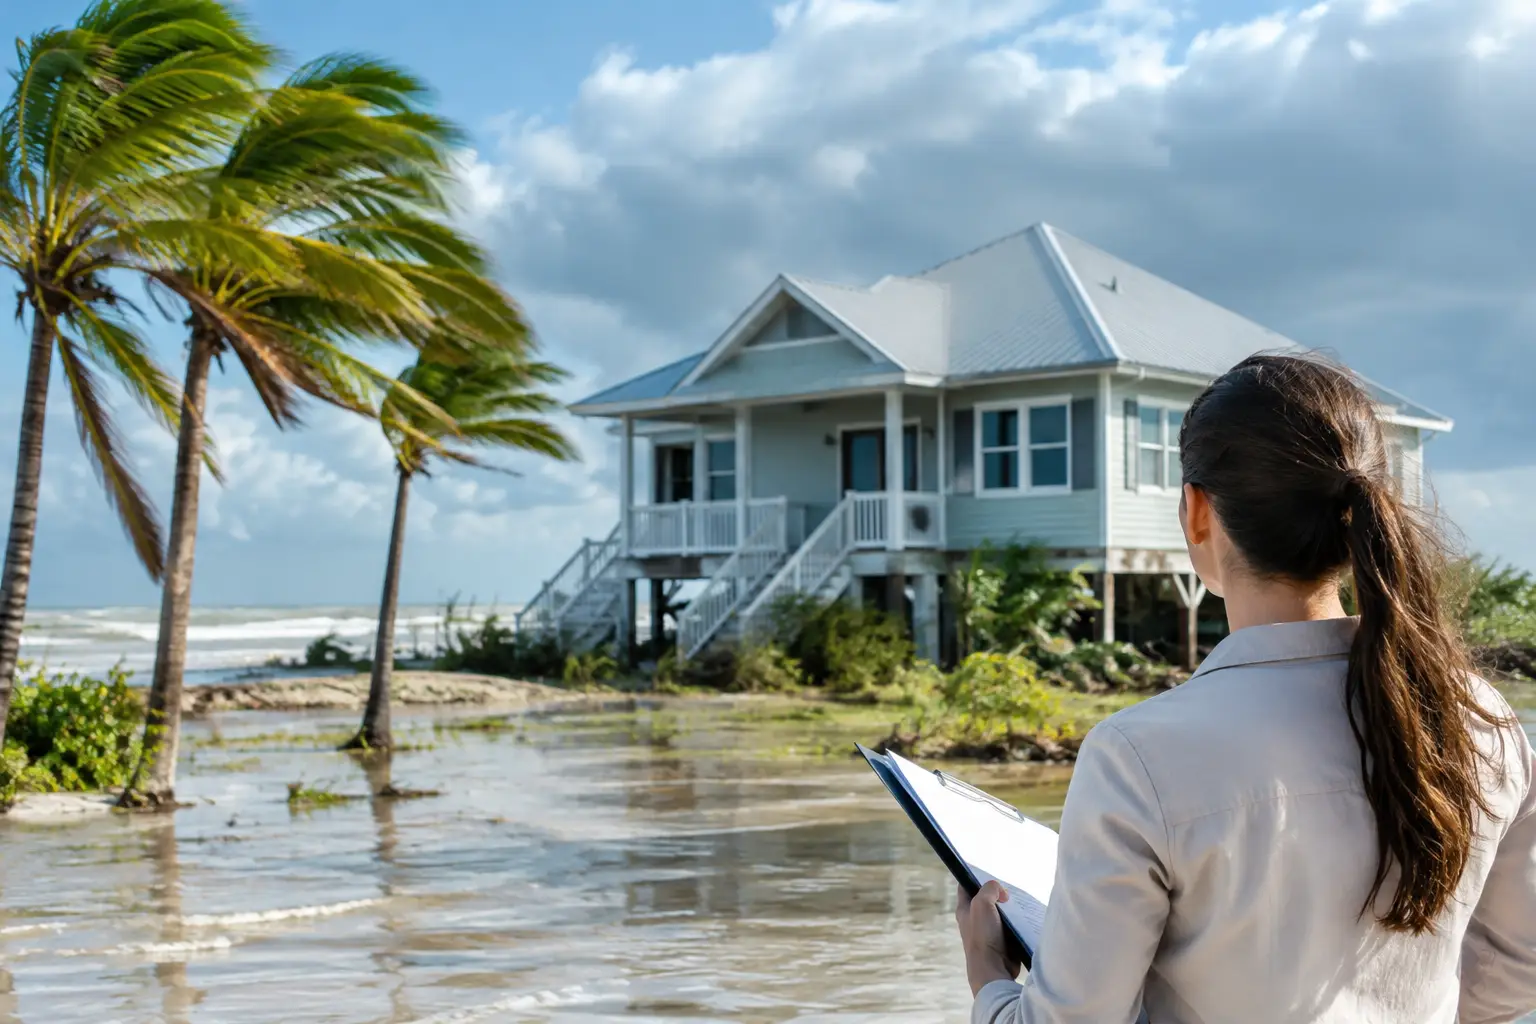
Standard homeowners insurance generally does not cover flood damage. That distinction matters on the Emerald Coast, where heavy rain, storm surge, tidal influence, and drainage conditions can create risk well beyond the most obvious waterfront parcels.
A home in a higher-risk flood zone may require flood insurance when financed, but a lower-risk designation should not be treated as a guarantee of no exposure. Flood maps are useful starting points, not complete risk assessments. Elevation, finished-floor height, prior flood events, drainage patterns, and nearby development all deserve review.
For investment buyers, flood cost should be modeled alongside wind coverage, property taxes, maintenance, HOA obligations, and expected rental revenue. A premium vacation rental can generate strong income, but its return should be measured after realistic carrying costs – not only against peak-season gross bookings.
Elevation and construction type matter
Raised homes, pilings, ground-floor enclosures, and the use of the lower level can all influence flood exposure and insurance requirements. Older coastal properties may have design characteristics that were acceptable when built but are less favorable under current underwriting standards or rebuilding rules.
Concrete block, reinforced construction, and newer elevated designs may offer advantages, though materials alone do not tell the whole story. A carrier will consider the complete structure, including roof configuration, openings, mechanical systems, and evidence of maintenance. For older homes with architectural appeal, a targeted renovation can improve both market positioning and insurability when the work addresses genuine risk rather than cosmetic updates alone.
Deferred Maintenance Raises More Than Repair Costs
Salt air accelerates wear. Humidity can expose weak ventilation and moisture-management systems. A coastal property that has been lightly used, rented heavily, or held as a seasonal residence may develop maintenance issues that are not immediately visible during a brief showing.
Common concerns include corroded fasteners, deteriorated exterior sealants, aging HVAC equipment, plumbing leaks, wood rot, inadequate drainage, and poorly maintained decks or balconies. These conditions can lead insurers to request repairs before binding coverage or to exclude certain types of damage.
The objective is not to avoid every home needing work. Value can often be created through disciplined renovation. The distinction is between a property with a clear, budgeted improvement plan and one with uncertain exposure across multiple major systems. The latter can erode negotiating leverage and create expensive surprises after closing.
How Buyers Should Evaluate Insurability Before Making an Offer
For a high-value coastal acquisition, insurance due diligence should begin alongside physical inspections and financial analysis. Request the age and type of the roof, a copy of any available wind mitigation report, flood-zone information, details on prior claims and repairs, and records for major upgrades. If the home has storm shutters, impact glass, a generator, or other protective features, confirm their specifications and condition.
Then obtain preliminary insurance guidance based on the actual property address, not a generic estimate. A qualified insurance professional can identify likely coverage options, deductible structures, required repairs, and whether flood coverage should be separately priced. This is particularly important for properties intended as vacation rentals, where vacancy periods, occupancy patterns, and commercial use may affect policy requirements.
Build an appropriate contingency into the contract when insurance is a meaningful variable. For cash buyers, the absence of lender requirements does not remove the risk. For financed buyers, coverage terms can directly affect the lender’s approval process and closing timeline.
Insurability Also Affects Resale Strategy
A property with a new roof, current mitigation documentation, completed permitted repairs, and a clean maintenance record is easier to position in the market. It gives future buyers more confidence and reduces the chance that insurance becomes a late-stage objection during negotiations.
For sellers, addressing insurance-sensitive items before listing can protect pricing power. This does not always mean undertaking a full renovation. Sometimes the highest-return work is targeted: replacing an aging roof, documenting impact protection, correcting drainage, servicing mechanical systems, or assembling permits and invoices for prior improvements.
Coastal real estate rewards informed ownership. Before committing to a property, treat its insurance profile as part of its investment thesis – a measurable component of risk, operating cost, and long-term marketability.